Across the Border, Through a Divorce: When One Spouse Works in Michigan
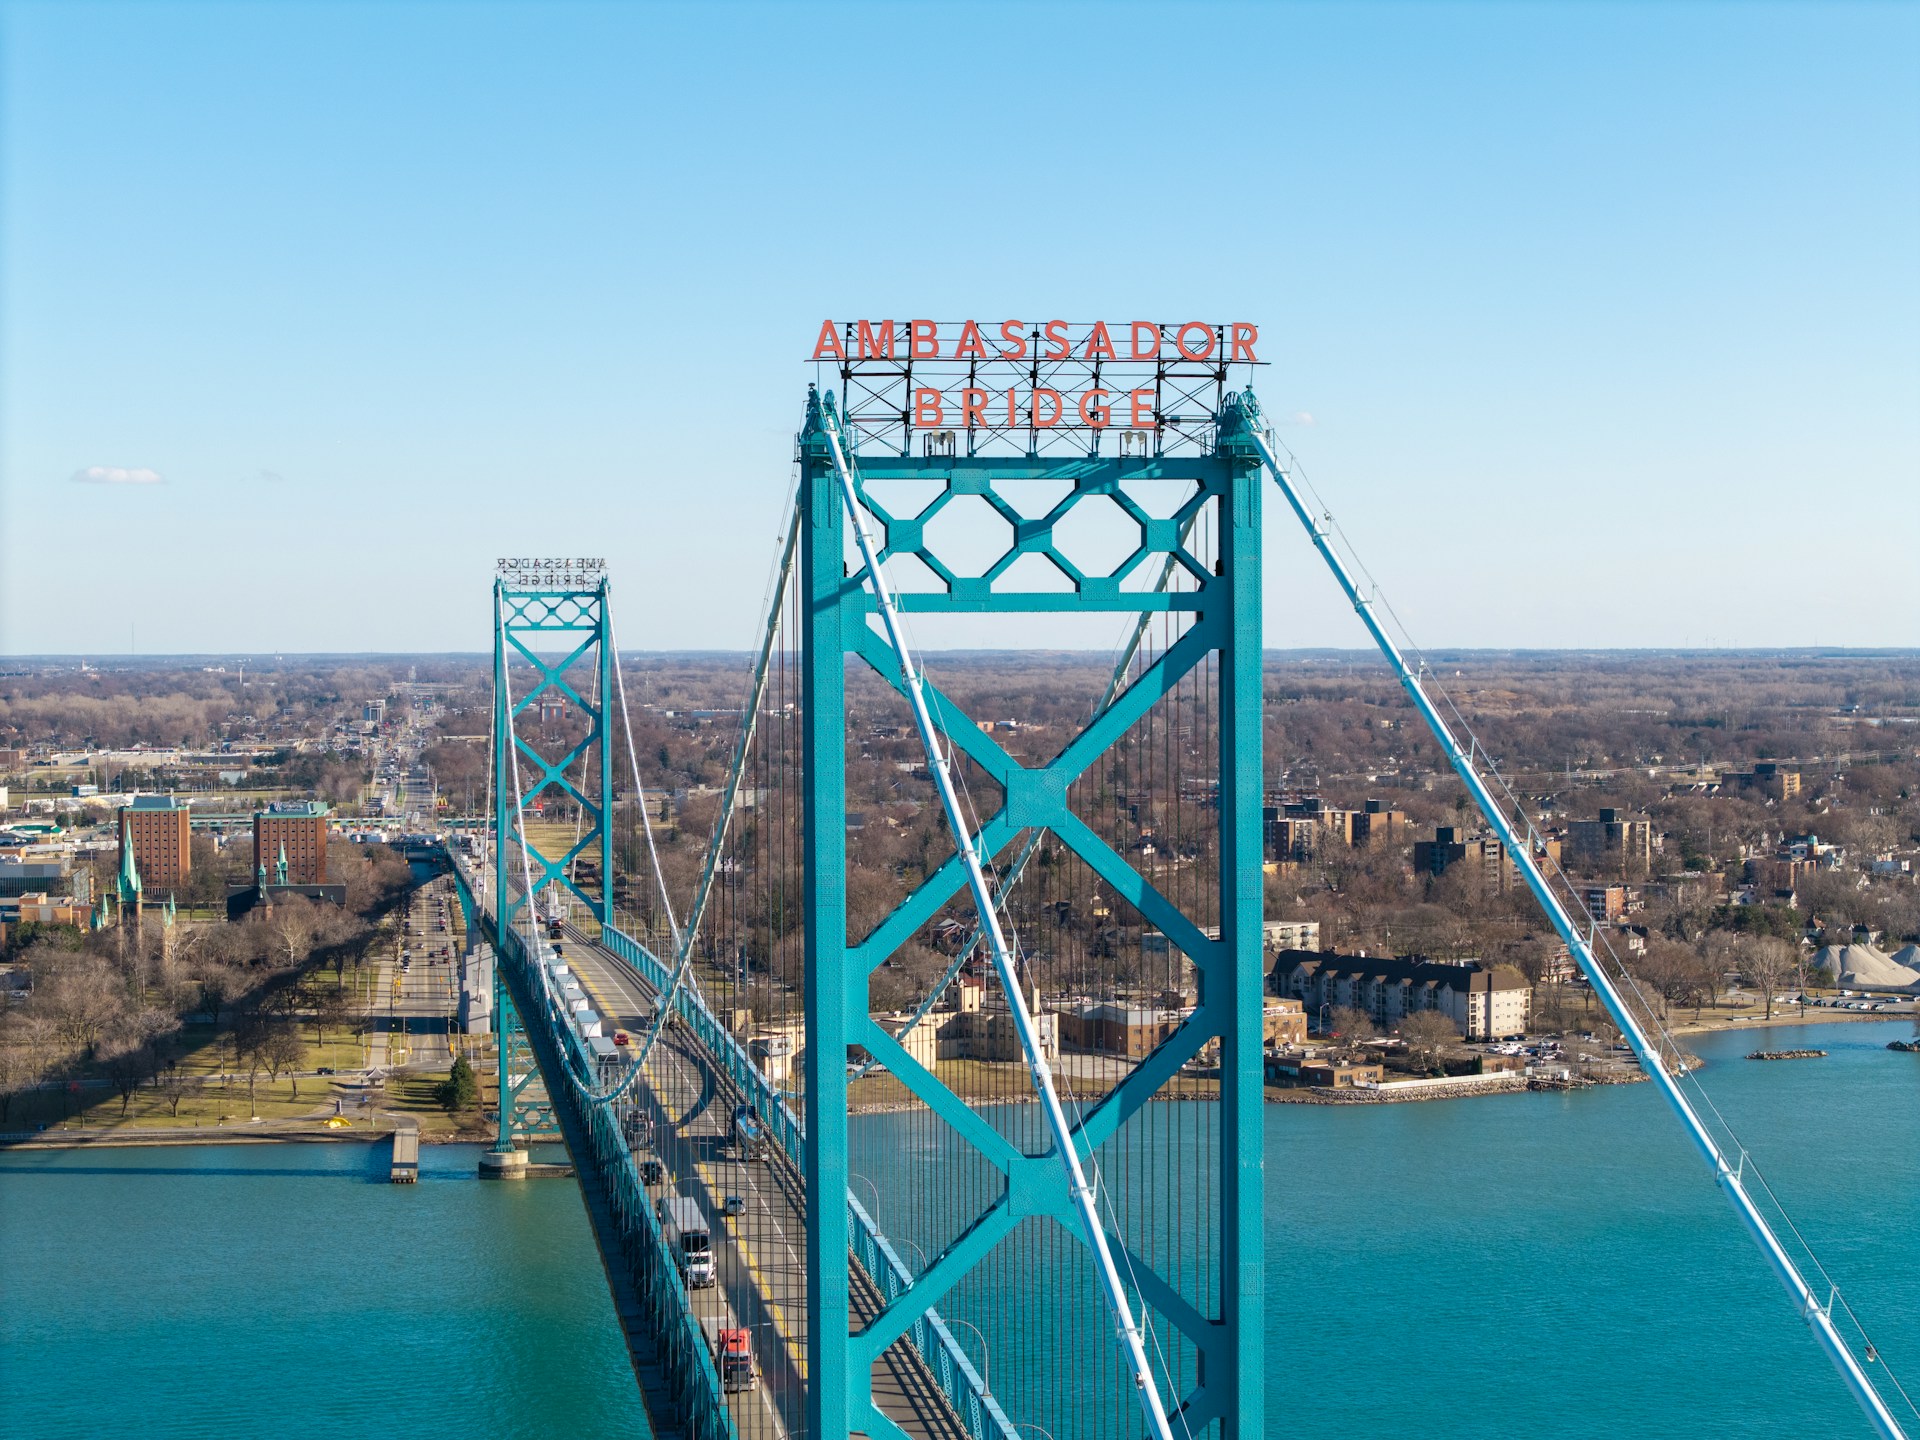
For many families in Windsor-Essex, crossing the Ambassador Bridge or Detroit-Windsor Tunnel is part of the ordinary workday. A spouse may live with their family in Ontario while earning a salary, bonuses, retirement benefits, or other compensation from an employer in Detroit or elsewhere in Michigan.
If the marriage ends, that cross-border employment can add another layer to an Ontario separation or divorce. Questions may arise about where the divorce should proceed, how U.S. income is calculated for support, how American retirement accounts are treated, and what happens when assets or support obligations extend across an international border.
Does Working in Michigan Affect Where an Ontario Divorce Is Filed?
Working in another country does not, by itself, determine where a divorce must take place. Under Canada’s Divorce Act, an Ontario court generally has jurisdiction over a divorce proceeding if either spouse has been habitually resident in Ontario for at least one year immediately before the proceeding begins.
As a result, a Windsor resident who commutes to Michigan for work may still be habitually resident in Ontario. Employment location and place of residence are separate considerations.
Jurisdiction can become more complicated if a spouse has actually moved to Michigan, maintains residences on both sides of the border, or if proceedings have been started in both Canada and the United States. Determining which court should address particular family law issues may then require closer consideration of the parties’ residence, connections to each jurisdiction, and the nature of the claims being made.
Michigan Income Can Still Be Relevant to Ontario Support
A spouse’s income does not disappear from an Ontario family law calculation simply because it is earned in U.S. dollars. Income from a Michigan employer may be relevant to both child support and spousal support.
Determining the appropriate income figure can require more documentation than a conventional Ontario employment arrangement. In addition to Canadian tax returns and notices of assessment, the financial record may include U.S. tax returns, W-2 statements, pay records, employment contracts, bonus information, and documents relating to stock-based or other employment compensation.
The Federal Child Support Guidelines also address situations involving non-residents of Canada. Generally, a non-resident spouse’s annual income is determined as though that person were resident in Canada, subject to specific provisions addressing significantly different tax rates. This may become particularly relevant if a spouse not only works in Michigan but also lives there following separation.
Converting U.S. Earnings Into Canadian Dollars
Another practical issue is currency. A salary of US$100,000 is not equivalent to C$100,000, and exchange rates can fluctuate considerably over time.
Where American earnings, accounts, or other assets are being considered in an Ontario family law proceeding, their values may need to be expressed in Canadian dollars. The applicable exchange rate and the date or period used for conversion can therefore affect the figures appearing in financial disclosure and calculations.
This can become particularly important where compensation varies throughout the year or consists of salary plus commissions, bonuses, restricted stock, or other benefits. Clear records of both the original U.S.-dollar amounts and their converted Canadian values can help explain how the figures were calculated.
Cross-Border Taxation Can Affect the Financial Picture
A Windsor-Essex resident who physically works in Michigan may also have tax obligations involving both Canada and the United States. The Canada-U.S. tax treaty contains rules addressing employment income earned by a resident of one country while employment is exercised in the other.
As a result, the amount shown on a Michigan pay statement may not tell the whole story about a spouse’s income or overall tax position. U.S. income tax paid, Canadian reporting obligations, available foreign tax credits, and other cross-border tax considerations may all form part of the financial background.
These issues can matter when reviewing the parties’ actual financial circumstances. They can also make it important to distinguish gross employment income from taxes withheld, employment-related deductions, and amounts ultimately reported for Canadian tax purposes.
What Happens to a 401(k), IRA, or U.S. Pension?
Michigan employment can also create property issues that do not ordinarily arise when both spouses work exclusively in Ontario. A spouse may have accumulated value through a 401(k), IRA, defined benefit pension, employer stock plan, or another U.S.-based retirement arrangement.
Ontario’s Family Law Act broadly includes interests in property when calculating a married spouse’s net family property. On separation, the spouse with the lower net family property is generally entitled to one-half of the difference between the spouses’ net family properties, subject to the Act’s rules concerning deductions and excluded property.
A U.S. retirement asset may therefore need to be identified and valued even though the plan administrator and funds are located outside Canada. Its tax characteristics, withdrawal restrictions, valuation method, and rules governing division may differ from those applying to an Ontario pension. In some circumstances, implementing an agreed or ordered division may also involve U.S. procedures or documentation.
Bonuses, Stock Options, and Other Michigan Employment Benefits
Cross-border employees may receive more than a base salary. Employment packages can include annual bonuses, signing incentives, restricted stock units, stock options, profit-sharing arrangements, deferred compensation, or employer retirement contributions.
These forms of compensation can create timing questions during a separation. For example, a bonus received after separation may relate partly or entirely to work performed before separation. Stock awards may have been granted during the marriage but vest later.
Different forms of compensation may also be relevant for different purposes. Their treatment when determining income for support is not necessarily identical to their treatment when valuing property for equalization. The terms of the employment and compensation plans, grant dates, vesting schedules, and underlying documentation may therefore become significant.
U.S. Bank Accounts and Other Assets Must Be Considered
A spouse working in Michigan may maintain a U.S. chequing account for payroll deposits, an investment account, employer shares, or other assets denominated in U.S. dollars.
Ontario’s property regime is not limited to property physically located within the province. The Family Law Act definition of property broadly encompasses interests in real and personal property. Accordingly, the financial disclosure process may involve assets held outside Canada as well as those held locally.
International assets can introduce additional questions concerning valuation, currency conversion, taxation, and the practical steps required to access or transfer property.
Can Ontario Support Orders Be Enforced in Michigan?
Cross-border enforcement may become important if one spouse moves to Michigan after separation or if the payor’s employment and assets are located there.
Ontario legislation recognizes the United States, including all 50 states, as reciprocating jurisdictions for interjurisdictional support purposes. Ontario’s interjurisdictional support framework provides processes for establishing, changing, registering, and enforcing certain support obligations where the parties live in different jurisdictions.
The particular procedure can depend on factors such as where each spouse lives, whether the support obligation arises under the federal Divorce Act or provincial legislation, and whether an order is being established, varied, or enforced.
Parenting Arrangements May Also Reflect Cross-Border Employment
Even where both parents and the children continue to live in Windsor-Essex, Michigan employment can affect the practical structure of parenting arrangements.
A parent’s workday may include international commuting, border delays, shift schedules, mandatory overtime, or irregular hours. These circumstances may be relevant when developing parenting schedules that address school transportation, exchanges, holidays, and unexpected delays.
If a parent later relocates to Michigan rather than merely working there, additional cross-border issues can arise concerning travel documents, transportation, parenting schedules, and the rules governing relocation.
Cross-Border Employment Calls for a Broader Financial Record
An Ontario divorce involving Michigan employment may ultimately remain an Ontario family law matter, but the evidence needed to address it can extend well beyond Ontario.
U.S. employment records, tax filings, retirement accounts, compensation plans, bank accounts, and exchange rates can all become relevant. Cross-border tax or pension issues may also require input from financial or tax professionals familiar with both Canadian and American systems.
For Windsor-Essex spouses accustomed to living in one country and working in another, recognizing these cross-border considerations early can help ensure that the full financial picture is identified as separation and divorce issues are addressed.
Contact Johnson Miller Family Law for Cross-Border Family Law Matters in Windsor-Essex County
The family and divorce lawyers at Johnson Miller Family Lawyers assist clients throughout Windsor, Essex County, Tecumseh, LaSalle, Amherstburg, Lakeshore, Leamington, and surrounding Southwestern Ontario communities with separation and divorce matters involving cross-border financial circumstances. If you or your spouse works in Detroit or elsewhere in Michigan, contact us online or call (519) 973-1500 to discuss your family law matter with a member of our experienced team.